Last updated: October 12, 2026
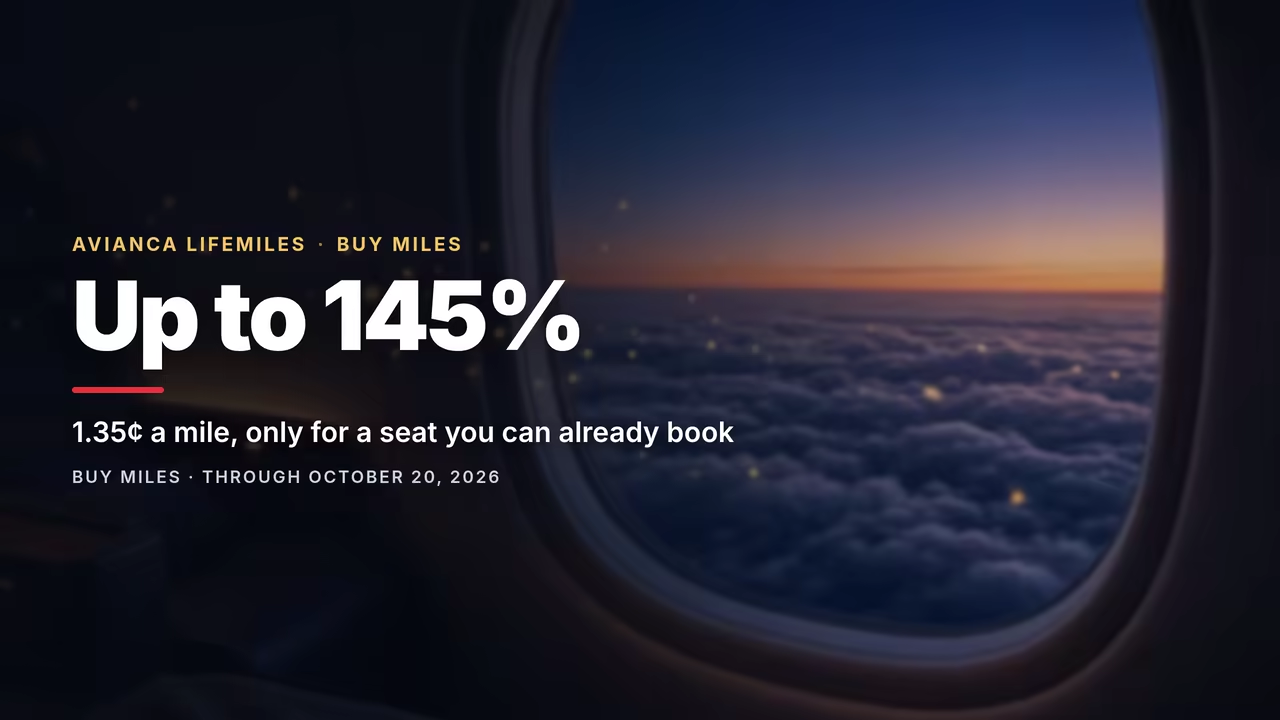
Avianca LifeMiles is selling miles with a bonus of up to 145% from October 12, 2026 through 11:59 p.m. Central time on October 20, 2026. The base price before any bonus is 3.3¢ a mile. At the top tier, 51,000 to 200,000 miles bought in one transaction come back at 1.35¢ each. A smaller purchase is a smaller bonus, and a higher price.
Find the award seat first. Then buy only the miles that ticket still needs. LifeMiles has already run this same 145% bonus twice in the last two months, on August 19–27 and September 16–25, and stronger sales at 160% and 170% have priced miles around 1.27¢ and 1.22¢. A balance you hope to use later is a bet that the next sale will be worse and that the seat will still be there.
Before you buy miles: Run your spending through the credit card rewards calculator. A buy-miles sale does not fix a wallet that should be earning a transferable currency. Citi ThankYou has a live 25% transfer bonus to LifeMiles through October 24, 2026, which outlasts this purchase window. Amex Membership Rewards, Capital One, Bilt, and Wells Fargo transfer at 1:1. Check those balances before you pay cash.
The promo, without the fluff
Log in and open the purchase page. The bonus and the total on that screen are the offer. One Mile at a Time says the standard offer across the accounts he checked is up to 145%, and that different members can be targeted for a different bonus, or for no bonus at all. A headline of 145% is your account when the page says 145%.
| Detail | What the sources actually say |
|---|---|
| Window | October 12, 2026 through 11:59 p.m. Central time on October 20, 2026. One Mile at a Time dates the start as October 12 and the end as October 20. Upgraded Points dates the end as 11:59 p.m. Central on October 20. No source we checked printed a start clock |
| Tiers | 125% on 1,000–20,000 miles bought, 135% on 21,000–50,000, 145% on 51,000–200,000. Upgraded Points, One Mile at a Time, and the September round covered by Milesopedia and AwardWallet all print those bands |
| Base price | 3.3¢ per mile before the bonus (One Mile at a Time; Milesopedia’s off-sale price is the same 3.30¢) |
| Price | About 1.47¢ at 125%, about 1.40¢ at 135%, 1.35¢ at 145%. The dollar examples below are the check on those rates |
| Who | Targeted. Confirm the bonus while you are logged in, before you pay |
| Where | The logged-in LifeMiles purchase page, lifemiles.com/miles/buy. Who processes the charge is disputed. See below |
| Per transaction | 200,000 miles bought. $6,600 becomes 490,000 miles at 145%, which is 1.35¢ |
| Worked example | 40,000 miles cost $1,320 and return 94,000 miles at the 135% tier, which is 1.40¢ (Milesopedia’s September example; the arithmetic is the same on this round) |
| Annual cap | About 500,000 miles a year. Sources disagree on whether bonuses count, and One Mile at a Time prints 200,000 a year. Read the terms on your purchase page |
| Steps | 1,000 miles at a time. The minimum purchase is 1,000 (AwardWallet’s September terms; Prince of Travel’s August terms) |
| Refunds | Non-refundable (AwardWallet’s September terms) |
| Posting | AwardWallet’s September terms allow up to 72 hours. Their users’ purchases typically posted within about 12 hours |
| This sale again | The same 145% bonus ran August 19–27 and September 16–25, 2026 (One Mile at a Time’s sale history) |
This sale is listed with the other active sales on the point sales page. Card transfer bonuses that are live this month are on the transfer bonuses page. A purchase is not a transfer bonus, so there is no LifeMiles row to add there for this sale. The live row that does belong on that page is the Citi to LifeMiles 25% transfer bonus, through October 24.
The cents above are the U.S. price in the published examples, before any tax a checkout might add. A receipt with a tax line is a higher price. Do not use 1.35¢ as your price if the screen shows a tax.
What you pay per mile
Every published dollar figure in this round divides by 3.3¢ per mile you buy. The bonus is extra miles, so the price per mile you receive is 3.3¢ divided by 2.25, 2.35, or 2.45.
| Miles you buy | Bonus | Miles you receive | Cash, before tax | Cents per mile received |
|---|---|---|---|---|
| 1,000 (the minimum) | 125% | 2,250 | $33 | 1.47¢ |
| 20,000 (top of the 125% band) | 125% | 45,000 | $660 | 1.47¢ |
| 40,000 (Milesopedia’s example) | 135% | 94,000 | $1,320 | 1.40¢ |
| 51,000 (the smallest 145% purchase) | 145% | 124,950 | $1,683 | 1.35¢ |
| 200,000 (the per-transaction maximum) | 145% | 490,000 | $6,600 | 1.35¢ |
$660 / 45,000 = 1.466¢, which rounds to 1.47¢. $1,320 / 94,000 = 1.404¢, which rounds to 1.40¢. $6,600 / 490,000 = 1.347¢, which rounds to 1.35¢. $1,683 / 124,950 is the same 1.347¢. Buying 200,000 miles does not get you a better rate than buying 51,000. It gets you more miles at the same rate, and a $6,600 receipt.
AwardWallet’s September writeup printed 1.53¢ on the 125% tier and 1.50¢ on the 135% tier, next to a 145% tier it priced at 1.35¢ and a $6,600 / 490,000 example. Those lower-tier cents do not fall out of a 3.3¢ base. The dollar examples do. Use the screen’s total divided by the miles the screen says you will receive.
A 20,000-mile purchase and a 21,000-mile purchase are different sales. 20,000 bought returns 45,000 miles for $660. 21,000 bought returns 49,350 miles for $693, which is 1.40¢. Stepping over a tier line only helps if you will use the miles the higher tier delivers.
The cap, and why the sources do not agree
Four writeups describe the yearly limit, and they do not describe the same limit.
- Upgraded Points, updated October 12, 2026: a maximum of 500,000 miles per calendar year before any bonuses.
- Milesopedia, describing the standing rule next to the September sale: 500,000 miles before the bonus, and a separate ceiling of 1,000,000 miles received per year, bonus included.
- AwardWallet’s September terms: a maximum of 500,000 LifeMiles annually, including any bonuses. The per-transaction maximum is 200,000 LifeMiles bought.
- Prince of Travel, on the August 19–27 sale: members can receive a maximum of 500,000 miles from purchases per calendar year, including bonus miles. That writeup treats one max transaction, 490,000 miles for $6,600, as just under the annual cap. That sentence only works if the bonus counts.
- One Mile at a Time, October 12, 2026: up to 200,000 miles per account per calendar year, before bonuses. That is the same number every other source uses for a single transaction.
The careful version is the one to shop with. About 500,000 miles a year. Check the terms on your purchase page. Miles you already bought in 2026 may already be sitting against that cap. A checkout that will not sell you the miles is a different offer from the headline, and the purchase is non-refundable once it goes through.
Price the seat, then buy the gap
Search the award before a dollar goes to the purchase page. LifeMiles does not always see the same Star Alliance space other programs see. One Mile at a Time’s note on this round is the useful one: sometimes LifeMiles lacks a seat another program can book, and sometimes the reverse is true. Upgraded Points’ October 12 redemption examples are planning prices. They are the price when your search says so.
LifeMiles partner awards are the reason people buy these miles. One Mile at a Time says the program does not add fuel surcharges on Star Alliance awards. This site’s Citi to LifeMiles article, following Frequent Miler, is more precise: LifeMiles generally skips carrier-imposed surcharges, and a partner booking fee around $25 can still apply, plus government taxes. The cash line on an award is small next to a program that piles on carrier charges. It is not zero. Read it on the ticket you are about to buy.
United Polaris, transcontinental, in Upgraded Points’ example. Upgraded Points says a one-way United business award from Newark (EWR) to Los Angeles (LAX) or San Francisco (SFO) is 25,000 LifeMiles. At the 1.35¢ top-tier rate, 25,000 miles are $337.50. That $337.50 figure is 25,000 × 1.35¢. It is the rate you pay when the purchase is already in the 145% tier. A top-up that only has to produce 25,000 miles is in the 125% tier. The smallest 1,000-mile step that covers 25,000 miles is 12,000 miles bought, which costs $396 and returns 27,000. If the leftover 2,000 miles have no seat, the award cost you $396, which is 1.58¢ on the 25,000 you fly. Search the flight. LifeMiles books United when partner space is there, and travelers on earlier rounds have reported premium United space as scarce. A 25,000-mile price with an empty calendar is a blog post.
Star Alliance business to Europe, in Upgraded Points’ October 12 range. SWISS, Turkish, Brussels, and similar partners, 70,000 to 80,000 LifeMiles one way. At 1.35¢ that is $945 to $1,080. Same caveat. Those products are the top-tier unit price. From a zero balance, 70,000 miles land in the 135% tier: buy 30,000 miles for $990 and receive 70,500. An 80,000-mile award is buy 35,000 for $1,155, receiving 82,250. The 145% tier starts at 51,000 miles bought, $1,683 for 124,950 miles. Pay that only if a second award will use the extra miles.
September coverage on this site already showed why you read the screen. AwardWallet’s example that week was New York (JFK) to Zurich in business at 55,000 LifeMiles. Upgraded Points’ same-week list included Boston to Zurich on SWISS at 69,000. The October 12 range of 70,000–80,000 sits next to those, not in place of them. Prices move. The number LifeMiles quotes for your date is the number.
Cash fares for those cabins are often several times the receipt. That comparison is the one that matters, and it includes the taxes and the partner booking fee on the award, and the taxes on the cash ticket you would actually buy. An award and a refundable cash fare are different products. Compare the fare you would buy.
Who processes the charge
The card you should put this on depends on the merchant, and the sources published on October 12 do not agree about the merchant.
- Upgraded Points, updated October 12: purchases are processed by Points.com, so they do not count as airfare. Their advice is an everyday-spending card, or a card whose welcome bonus the charge helps you finish.
- One Mile at a Time, October 12: the purchase is processed by LifeMiles, so it does qualify as airfare, and a card that earns a bonus on airlines is the one to consider.
- Prince of Travel, on the August sale: Avianca had moved off Points.com and back to selling on its own site, so the charge coded as an airline purchase.
- AwardWallet, September: Avianca has gone back and forth between selling miles directly, which coded as airfare, and selling them through Points.com.
Read the merchant name on the payment page before you pick a card. A Points.com charge is an everyday purchase. A charge that shows Avianca may be airfare. Guessing wrong does not change the miles you receive. It changes the points the card earns on a non-refundable payment.
Transfers first, especially Citi through October 24
LifeMiles is a transfer partner of several currencies this site tracks. The ratios below are how those pages list the partner as of October 2026. Upgraded Points also lists Brex. This site does not publish a Brex ratio, so read the Brex screen before you count on one. Chase Ultimate Rewards does not list LifeMiles.
The Points Guy’s October 2026 valuations put a LifeMile at 1.6¢, up from 1.55¢. That is the figure this site’s tools use. Upgraded Points values a LifeMile at 1.4¢. One Mile at a Time’s own figure is about 1.3¢. A mile you buy at 1.35¢ is about 16% under TPG’s 1.6¢, a little under Upgraded Points’ 1.4¢, and a little over One Mile at a Time’s 1.3¢. On the point sales page, 1.35¢ against 1.6¢ is near typical value. The “cheaper than typical value” line on that page is 80% of the valuation, which is 1.28¢. A 160% sale at about 1.27¢ is the one that crosses it. This 145% sale does not.
| How you get one LifeMile | What it costs on those figures |
|---|---|
| Buy it at 145%, from 51,000 miles | 1.35¢ cash, before tax |
| Buy it at 135%, from 21,000 miles | 1.40¢ |
| Buy it at 125%, from 1,000 miles | 1.47¢ |
| Transfer Amex, Capital One, Bilt, Wells Fargo, or U.S. Bank at 1:1 | 2.0¢, 1.85¢, 2.2¢, 1.75¢, or 1¢ |
| Transfer Citi on an annual-fee card, with the 25% bonus | 1.52¢ (1.9¢ / 1.25) |
| Transfer Citi on a select no-fee card, with the 25% bonus | 2.17¢ (1.9¢ / 0.875) |
| Transfer Marriott at 3:1, with no 5,000-mile bonus | 2.25¢ (3 × 0.75¢) |
The 1¢ on U.S. Bank is this site’s cash-redemption fallback. TPG does not publish a U.S. Bank valuation. U.S. Bank has listed LifeMiles at 1:1 since August 11, 2026. A transfer of points you would otherwise cash out at 1¢ can beat this sale. Confirm the ratio on your screen.
Citi is the transfer to price first, because the bonus is live and it lasts four days past this purchase window. On an annual-fee card (Strata Elite, Strata Premier, Prestige, AT&T Access More), 1,000 ThankYou Points become 1,250 LifeMiles through 11:59 p.m. ET on October 24, 2026. On a select no-fee card, AwardWallet’s reported bonus ratio is 1,000 to 875, against a standard 1,000 to 700. The Citi article is the full version of that offer, including the expiry and the booking quirks. The short version for this sale: if the screen shows 1,250, transfer the gap before you buy miles.
Marriott Bonvoy moves to LifeMiles at 3:1, and LifeMiles is one of the partners that does not get the 5,000-mile bonus most airlines get on a 60,000-point transfer. 60,000 Bonvoy points become 20,000 LifeMiles, not 25,000. Prince of Travel’s August buy-miles piece described a 5,000-mile bonus on this partner. This site’s transfer page does not. Use the page. At 0.75¢ a Bonvoy point, manufacturing LifeMiles out of Marriott is 2.25¢ a mile, well above every tier of this sale. Move Bonvoy points when you are a few thousand miles short and a 3:1 top-up is smaller than the next purchase tier. Do not move them to dodge a receipt you were willing to pay.
Two gaps show the order of operations.
A 25,000-mile award, the Polaris example, from a zero balance.
| How you cover 25,000 LifeMiles | What it costs |
|---|---|
| Buy 12,000 miles at 125% | $396 before tax. You receive 27,000 |
| Transfer 20,000 Citi points on an annual-fee card | 25,000 LifeMiles. About $380 at 1.9¢ |
| Transfer 25,000 Amex points | About $500 at 2.0¢ |
| Transfer 25,000 Capital One miles | About $463 at 1.85¢ |
| Transfer 25,000 Bilt points | About $550 at 2.2¢ |
| Transfer 25,000 Wells Fargo points | About $438 at 1.75¢ |
| Transfer 75,000 Marriott points at 3:1 | 25,000 LifeMiles. About $563 at 0.75¢ |
A 70,000-mile award, the low end of Upgraded Points’ Europe range.
| How you cover 70,000 LifeMiles | What it costs |
|---|---|
| Buy 30,000 miles at 135% | $990 before tax. You receive 70,500 |
| Buy 51,000 miles at 145% | $1,683. You receive 124,950. The extra miles need a second seat |
| Transfer 56,000 Citi points on an annual-fee card | 70,000 LifeMiles. About $1,064 at 1.9¢ |
| Transfer 70,000 Amex points | About $1,400 |
| Transfer 70,000 Capital One miles | About $1,295 |
| Transfer 70,000 Bilt points | About $1,540 |
| Transfer 70,000 Wells Fargo points | About $1,225 |
On a priced award, buying at $396 or $990 is close to the planning cost of the Citi bonus, and cheaper than moving Amex, Bilt, Capital One, or Wells Fargo on these figures. The Citi points are points you already earned. The receipt is new cash. Transfer when the points are spare and the screen shows 1,250. Buy when you would rather keep those points for a redemption worth more than this award, and the cash fare loses to the purchase.
A no-fee Citi card at 875 LifeMiles per 1,000 points is a weak way into this award. 25,000 LifeMiles takes 29,000 points and returns 25,375 miles, about $551 at 1.9¢, which is more than the $396 purchase. Keep a no-fee ThankYou balance for a partner that prices it better, or for a premium Citi card you already decided to hold.
Buying 51,000 miles because you are 25,000 short is $1,683 for a top-off. That is the version of this sale that looks cheap per mile and spends money you did not need to spend.
When to buy
Pay for the miles only when all of these are true:
- The seat is already in your LifeMiles search. A specific flight, cabin, date, mileage price, and cash line you would actually pay. The 25,000-mile and 70,000–80,000-mile figures are Upgraded Points’ examples on October 12. They are the price when your search says so.
- Your purchase page shows the bonus for the tier you are about to buy. The screen’s total is the total. A targeted offer that is missing is a different sale.
- The cash fare loses. The cash price of the ticket you would buy, including the taxes that fare charges, is greater than the purchase total for the miles you still need, plus the taxes and any partner booking fee on the award. Use the tier the purchase actually falls in. Add tax if the receipt adds it.
- You will use the miles the purchase delivers. A 25,000-mile gap is a $396 purchase at 125%, or a 20,000-point Citi transfer. A 70,000-mile gap is a $990 purchase at 135%, or a 56,000-point Citi transfer. A 51,000-mile purchase is for an award that will consume what 124,950 miles can book.
- A transfer is the wrong place to manufacture this pile. Citi at 1,250 through October 24 is the first place to look. Amex, Capital One, Bilt, and Wells Fargo at 1:1 cost more on the planning figures than buying, so keep those points when a better award is the reason you hold them. Marriott at 3:1 without the 5,000-mile bonus is a top-up, not a substitute for this sale.
- The cap still has room. About 500,000 miles a year, and the purchase page is the version that applies to you. Count what you have already bought in 2026.
- The award can survive the posting delay. AwardWallet’s September terms allow up to 72 hours, and their users often see the miles within about 12 hours. Buy while the seat is on the screen. The bonus follows a purchase completed by 11:59 p.m. Central on October 20.
The clean yes: you are short a known number of miles for an award you have already priced, a Citi transfer at 1,250 would spend points you still want, the purchase page shows the tier you calculated, and the cash fare is higher than the receipt.
When to leave the cash alone
Skip the sale if any of these are true:
- Nothing is bookable. Buying 200,000 miles on October 20 because a headline says 145%, then searching an empty calendar, is $6,600 for 490,000 miles you hope LifeMiles will still price kindly. The same 145% bonus already ran in August and September. 160% and 170% sales have priced miles at about 1.27¢ and 1.22¢. That is the expensive version of a promo that keeps coming back.
- Your screen does not show the bonus. One Mile at a Time says the offer is targeted. Earlier rounds of this promo drew a long comment thread of accounts that saw nothing. A checkout with no bonus is 3.3¢ a mile. Do not pay a 145% headline against a different checkout.
- The cash fare is the ordinary one. A short-haul ticket that is cheap in dollars is a ticket to pay for in dollars. A 7,500-mile domestic United award, which is where some September coverage started, is a transfer or a small top-up. It is a poor reason to open a five-figure purchase.
- You would be buying up to the next tier and calling the leftovers free. 51,000 miles for a 25,000-mile seat is $1,683 so the rate can say 1.35¢. The miles you do not have a seat for are the part of the receipt you did not need.
- You hold Citi points and the transfer screen shows 1,250. Through October 24, 20,000 ThankYou Points become the 25,000 LifeMiles in the Polaris example, and 56,000 become 70,000. That is the path that does not spend new cash. The transfer bonus article is the one to read before you buy.
- The only ThankYou card you hold charges no annual fee, and you were about to transfer at 875. 875 LifeMiles per 1,000 points costs more, on the 1.9¢ figure, than buying at 125% or 135%. Leave the points at Citi.
- You would be moving Marriott to avoid the receipt. 3:1 with no 5,000-mile bonus turns a 0.75¢ hotel point into a LifeMile that cost 2.25¢. Buy the miles, or use the Bonvoy points on a hotel.
- The cap is already used. A non-refundable charge for miles that will not post is the worst outcome on this page.
- The seat is fragile and you are counting on a slow post. 72 hours is the published window from the September terms. A seat that will not survive the afternoon is a seat to book with miles you already hold.
LifeMiles also expire. One Mile at a Time says the miles last as long as you accrue some at least once every 12 months, that buying miles extends that clock, and that redeeming miles does not. Prince of Travel’s August writeup says earning or redemption resets it. The Citi article follows Frequent Miler: the miles expire after about a year of inactivity. A purchase you make for a seat you will fly this year starts a clock you can live with. A purchase you make for a seat you might fly in 2028 is a balance you have to keep awake.
The verdict
Buy LifeMiles in this window only for a seat you can already find, at the bonus your own purchase page shows, after you have checked the Citi transfer that runs through October 24.
The clock is October 12, 2026 through 11:59 p.m. Central on October 20, 2026. The bonus is 125% up to 20,000 miles, 135% from 21,000 to 50,000, and 145% from 51,000 to 200,000. The base price is 3.3¢. The top tier is 1.35¢. 200,000 miles cost $6,600 and become 490,000. 40,000 miles cost $1,320 and become 94,000, at 1.40¢. A 25,000-mile award bought from zero is a $396 purchase at 125%, not the $337.50 you get by multiplying 25,000 by the top-tier rate. A 70,000-mile award bought from zero is $990 at 135%.
The Points Guy’s October 2026 valuation is 1.6¢. This price is about 16% under that, which is near it, and it is a little under Upgraded Points’ 1.4¢. It is not the cheapest LifeMiles have sold for. The same 145% bonus ran in August and September. 160% and 170% sales have reached about 1.27¢ and 1.22¢.
The yearly cap is about 500,000 miles. Upgraded Points says that is before bonuses. AwardWallet and Prince of Travel say bonuses count. One Mile at a Time says 200,000 a year. Read the purchase page. The purchase is non-refundable. Whether it codes as airfare depends on whether the merchant is Points.com or Avianca, and the October 12 writeups disagree, so read the merchant too.
20,000 Citi points on an annual-fee card become 25,000 LifeMiles through October 24, about $380 on a 1.9¢ planning figure, against $396 to buy a 125% top-up. 56,000 Citi points become 70,000 LifeMiles, about $1,064, against $990 to buy them at 135%. Transfer when the points are spare. Buy when the cash fare loses and you would rather keep the bank points.
Find the seat. Read the cash line. Read the bonus on your purchase page. Then buy exactly the miles that award requires.
Before you earn the next mile toward a LifeMiles award, run your spending through the credit card rewards calculator.
See this sale with the other active point sales →.
See all active transfer bonuses →.
Disclaimer / sources
This article reflects the Avianca LifeMiles buy-miles promotion reported on October 12, 2026. Checked October 12, 2026.
- Upgraded Points, updated October 12, 2026 at 1:38 p.m. CDT: through October 20, 2026 at 11:59 p.m. Central; 125% on 1,000–20,000, 135% on 21,000–50,000, 145% on 51,000–200,000 at 1.35¢ each; $6,600 for 200,000 miles bought returns 490,000 miles; a calendar-year cap of 500,000 miles before bonuses; Points.com processes the purchase, so it does not code as airfare; United Polaris EWR–LAX/SFO one-way business at 25,000 LifeMiles, $337.50 at 1.35¢; Star Alliance business to Europe on SWISS, Turkish, Brussels, and similar partners at 70,000–80,000 one way, $945–$1,080 at 1.35¢; transfer partners listed as Amex Membership Rewards, Bilt, Brex, Capital One, Citi ThankYou, Marriott Bonvoy, and Wells Fargo; Upgraded Points values a LifeMile at 1.4¢. A logged-in purchase page was not available for this check. Confirm the bonus, the tax, and the cap on your own account.
- One Mile at a Time, October 12, 2026: starts October 12 and ends October 20, 2026; the same three tiers; base price 3.3¢; 200,000 miles bought with a 145% bonus is 490,000 miles for $6,600, or 1.35¢; offers are generally targeted; his personal valuation is about 1.3¢; no fuel surcharges on Star Alliance partner awards; he prices a yearly cap at 200,000 miles per account before bonuses; he says the purchase is processed by LifeMiles and qualifies as airfare; miles do not expire if you accrue some at least once every 12 months, buying miles extends that, and redeeming does not. His sale-history table on the same page lists 145% for August 19–27 and September 16–25, 2026, 130% for July 15–24, 160% for April 15–28, March 12–26, and January 9–19, 155% for February 9–23, and, looking back, 170% for November 10–18, 2025. Reader comments on earlier rounds of this post include accounts that saw no bonus, and comments that premium United space has been scarce. Those comments are not the offer.
- Milesopedia, describing the September 16–25, 2026 round (the page still called that round ended when checked October 12, and it had not yet posted this October window): off-sale price 3.30¢; 40,000 miles cost $1,320 and returned 94,000 at 1.40¢; the same three tiers; annual cap 500,000 before the bonus, with a separate ceiling of 1,000,000 miles received per year including bonuses; maximum 200,000 per transaction; Points.com, so the charge is not treated as travel. The tier math in that example matches this October round. The “no new round” line on that page does not.
- AwardWallet, September 16, 2026 writeup, still describing the sale that ended September 25 when checked October 12: through 11:59 p.m. GMT-6 on September 25; 1,000-mile increments; annual maximum of 500,000 LifeMiles including bonuses; 200,000 per transaction; non-refundable; terms allow up to 72 hours to post, and their users typically saw miles within about 12 hours; 145% tier at 1.35¢ with the $6,600 / 490,000 example. The same page prints 1.53¢ at 125% and 1.50¢ at 135%, which do not divide out of a 3.3¢ base. Its history table prices a 170% bonus at 1.22¢ and a 160% bonus at 1.27¢. It also says Avianca has flipped between selling miles directly, which coded as airfare, and selling them through Points.com.
- Prince of Travel, August 20, 2026, on the August 19–27 sale that page now marks as ended: the same three tiers; base price 3.3¢; 1.35¢ at 145%; 200,000 per transaction and $6,600 for 490,000 miles; a yearly cap of 500,000 miles received from purchases, including bonuses, with that 490,000-mile result described as just under the cap; targeted; 1,000-mile increments and a 1,000-mile minimum; at that time, Avianca had moved back to selling directly, so the charge coded as an airline purchase. That page’s transfer section says Amex, Capital One, and Citi transfer to LifeMiles, with Citi at 1:1 on a premium card and 1,000 to 700 otherwise, and it describes a 5,000-mile Marriott bonus on LifeMiles. This site’s Marriott transfer page lists LifeMiles at 3:1 with no 5,000-mile bonus. Use the transfer page.
- 1.47¢ is $660 / 45,000 and $33 / 2,250, from 3.3¢ / 2.25. 1.40¢ is $1,320 / 94,000, from 3.3¢ / 2.35. 1.35¢ is $6,600 / 490,000 and $1,683 / 124,950, from 3.3¢ / 2.45. $6,600 is 200,000 × $0.033. $1,320 is 40,000 × $0.033. $1,683 is 51,000 × $0.033. $396 is 12,000 × $0.033, and 12,000 × 2.25 = 27,000. $990 is 30,000 × $0.033, and 30,000 × 2.35 = 70,500. $1,155 is 35,000 × $0.033, and 35,000 × 2.35 = 82,250. $337.50 is 25,000 × 1.35¢. $945 is 70,000 × 1.35¢. $1,080 is 80,000 × 1.35¢. 1.58¢ is $396 / 25,000. About 16% is (1.6 − 1.35) / 1.6. 1.28¢ is 0.8 × 1.6. 1.22¢ is 3.3 / 2.70. 1.27¢ is 3.3 / 2.60. 1.52¢ is 1.9 / 1.25. 2.17¢ is 1.9 / 0.875. 2.25¢ is 3 × 0.75.
- Transfers. Amex, Capital One, Citi (annual-fee cards), Bilt, Wells Fargo, and U.S. Bank to LifeMiles at 1:1, and Marriott at 3:1 with no 5,000-mile bonus, are how this site’s transfer-partner pages list those partners as of October 2026. Chase Ultimate Rewards does not list LifeMiles. U.S. Bank’s 1:1 listing dates from August 11, 2026 on that page. 2.0¢, 1.85¢, 1.9¢, 2.2¢, 1.75¢, 0.75¢, and 1.6¢ are The Points Guy’s October 2026 valuations for Membership Rewards, Capital One, ThankYou Rewards, Bilt, Wells Fargo, Marriott Bonvoy, and Avianca LifeMiles, fetched October 12, 2026. LifeMiles at 1.6¢, up from 1.55¢, is the new row in this site’s valuations table; the other figures were already the ones the calculators use. 1¢ is this site’s cash fallback for U.S. Bank points, which TPG does not value. $380 is 20,000 × 1.9¢. $1,064 is 56,000 × 1.9¢. $500 is 25,000 × 2.0¢. $463 is 25,000 × 1.85¢, rounded from $462.50. $550 is 25,000 × 2.2¢. $438 is 25,000 × 1.75¢, rounded from $437.50. $563 is 75,000 × 0.75¢, rounded from $562.50. $1,400 is 70,000 × 2.0¢. $1,295 is 70,000 × 1.85¢. $1,540 is 70,000 × 2.2¢. $1,225 is 70,000 × 1.75¢. $551 is 29,000 × 1.9¢. 29,000 × 0.875 = 25,375.
- Citi bonus. 1,000 to 1,250 on annual-fee cards and 1,000 to 875 on select no-fee cards, through 11:59 p.m. ET on October 24, 2026, is the offer covered in the Citi to LifeMiles article. The partner booking fee around $25, the 12-month inactivity expiry, and the warning that LifeMiles’ cash line can be wrong until late in the booking are that article’s Frequent Miler citations, not a new checkout from October 12.
- Related MaxPoints pages: point sales, transfer bonuses, Citi to LifeMiles 25% bonus, Amex transfer partners, Capital One transfer partners, Citi transfer partners, Bilt transfer partners, Wells Fargo transfer partners, Marriott Bonvoy transfer partners, U.S. Bank transfer partners.
Offers can end early. Confirm the bonus, the tax, the cap, the merchant, and the award price on your own LifeMiles account before you pay.