Last updated: October 7, 2026
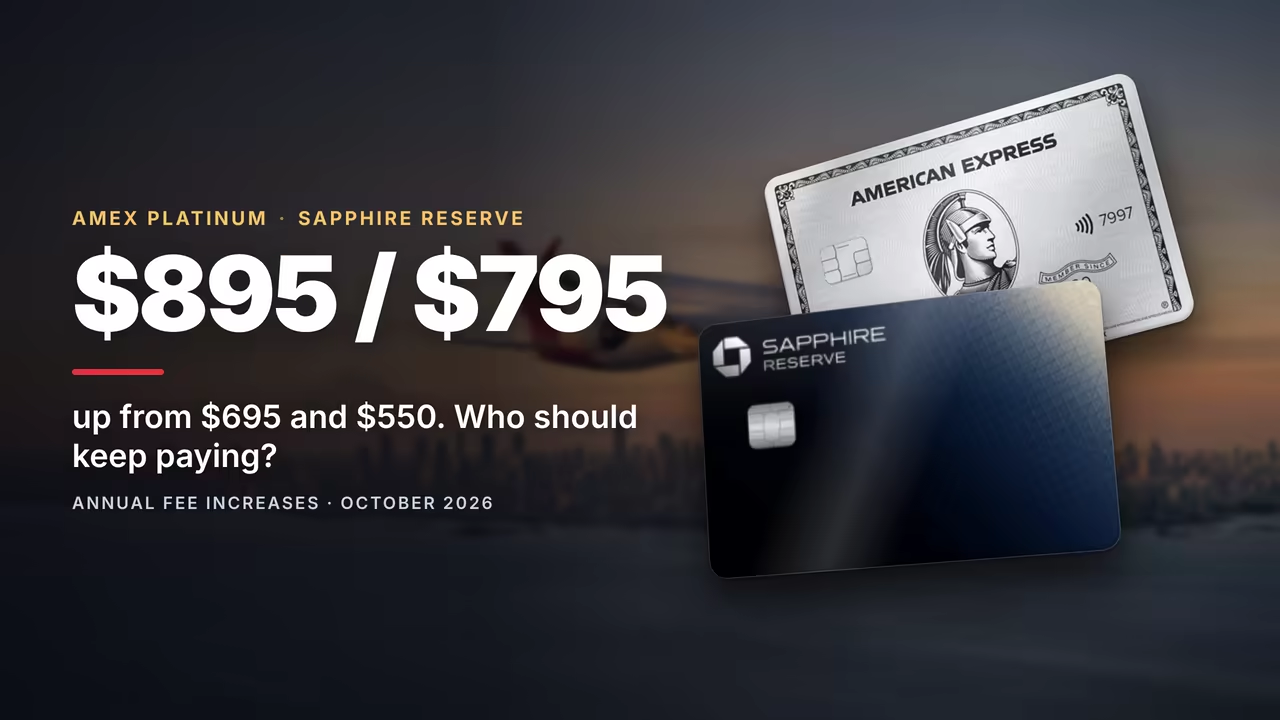
The two best-known premium travel cards both got a lot more expensive in 2025. The Amex Platinum went from $695 to $895, and the Chase Sapphire Reserve went from $550 to $795. By now every cardholder, old or new, is paying the higher fee at renewal.
Both issuers paired the increase with a long list of new credits, so the headline number tells you very little. What matters is whether you use enough of the new stuff to come out ahead.
My short verdict: the Platinum fee is only worth it if you would spend about $900 of its credits anyway. The Reserve is the easier card to keep, because its biggest credits are simpler to use. If neither describes you, your renewal notice is the moment to change cards, not to pay.
The Fee Increases at a Glance
| Old fee | New fee | Increase | |
|---|---|---|---|
| Amex Platinum | $695 | $895 | +$200 (about 29%) |
| Chase Sapphire Reserve | $550 | $795 | +$245 (about 45%) |
The Reserve’s jump is bigger, but the Platinum is now the more expensive card by $100. Citi’s competing Strata Elite sits at $595, so it undercuts both. Authorized users cost $195 on both the Platinum and the Reserve (the Reserve’s was $75 before).
When Each Increase Took Effect
Chase Sapphire Reserve:
- June 23, 2025: new applicants got the new card at $795.
- October 26, 2025: existing cardholders got the new benefits.
- Renewals on or after that date are billed at $795. If your renewal landed before October 26, 2025, you paid $550 one last time.
Amex Platinum:
- September 2025: Amex announced the refresh. New applicants paid $895 right away, and existing cardmembers got the new benefits immediately.
- January 2, 2026: the first renewal date on which existing personal Platinum cardmembers were charged $895.
If you are reading this in October 2026, any renewal you have coming is at the new price. There is no more grace period.
What Changed With the Credits
Amex Platinum
The Platinum’s story is credits, and lots of them. Amex says roughly $3,000 a year is available on paper. The notable changes:
- Hotel credit: $200 a year became up to $600 a year ($300 each half), on prepaid Fine Hotels + Resorts or The Hotel Collection stays booked through Amex Travel.
- Digital entertainment: $20 a month became $25 a month, with more eligible services.
- New credits: Resy ($400 a year), lululemon ($300), Oura Ring ($200) and an Uber One membership credit ($120). The catalog also lists an Equinox credit ($300) and a Walmart+ credit ($155).
- Other credits that carry over or moved: airline fee credit ($200), Uber Cash ($15 a month plus $20 in December), CLEAR+ (raised to $219 in July 2026).
- Since then: the Saks credit ended June 30, 2026, and Centurion Lounge guests must now be on the same flight as the cardmember.
The earn rate did not change. It is still 5x on flights booked directly with airlines or through Amex Travel and on prepaid Amex Travel hotels, and 1x on everything else.
Chase Sapphire Reserve
Chase reworked both the credits and the earn rates:
- Chase Travel (including The Edit) went from 5x to 8x.
- Flights and hotels booked direct went from 3x to 4x.
- Other travel fell from 3x to 1x. This is the quiet loss for anyone who books through Expedia or similar sites.
- Dining stayed at 3x, everything else at 1x.
- Credits: a $300 annual travel credit, up to $500 a year for The Edit hotel collection, up to $300 at Sapphire Reserve Exclusive Tables restaurants, a $300 StubHub and viagogo credit, $120 of Lyft, a $120 Peloton credit and DoorDash perks. Several of these run only through 2027 and need activation.
The Test I Use: Count Only the Credits You Would Buy Anyway
A credit is not a refund. It is a coupon for something specific. If you would not have spent that money, the credit is worth nothing, and the fee is the only thing that is real.
So here is the test. Add up only the credits for things you already pay for. Then compare against the fee.
| Fee | Credits that most travelers genuinely use | Fee covered? | |
|---|---|---|---|
| Amex Platinum | $895 | Uber Cash and Uber One ($320), digital entertainment ($300), airline fees ($200), one semi-annual hotel credit ($300) = $1,120 | Yes, with $225 to spare |
| Chase Sapphire Reserve | $795 | $300 travel credit, $300 Exclusive Tables dining, plus any you already pay for such as Lyft, StubHub or Peloton | Only if you use dining and the extras |
For the Platinum, the credits I listed total $1,120, and that is before the lounges, the 5x earning or a welcome bonus. The catch is that each of those is monthly, quarterly or semi-annual, requires enrollment and does not roll over.
The Reserve’s $300 travel credit is the easy one, because it applies automatically to a wide range of travel purchases. After that, the value depends on whether you eat at Exclusive Tables restaurants and already use Lyft, StubHub or Peloton. In the MaxPoints catalog, the Reserve’s modeled credits come to about $1,790 at face value, but the calculator leaves them switched off until you say you would use them.
Who Should Re-Evaluate
Keep the Platinum if you fly often, book flights directly with airlines (5x on up to $500,000 a year), take the lounge access seriously and would use at least four of its big credits without bending your habits.
Keep the Reserve if you use the $300 travel credit and the dining credit, book through Chase Travel, or want Chase Ultimate Rewards points that transfer to partners like Hyatt and United.
Re-evaluate the Platinum if you only use one or two credits, or you got the card mainly for the welcome bonus. At $695 it was borderline for you. At $895 it likely is not.
Re-evaluate the Reserve if you booked travel through third-party sites. Your old 3x on all travel is now 1x, and the fee went up $245.
Look at a cheaper card if you are paying a premium fee mainly for the points. The Amex Gold is $325 and earns 4x on dining and U.S. supermarkets, and the Chase Sapphire Preferred is $95. Neither has the lounges or the credit stack, but both keep you in the same points ecosystem. Before the renewal date, ask the issuer which downgrade options exist for your card.
Run Your Own Numbers
- Is the Amex Platinum worth it? Toggle each credit you would actually use and see the net result against the $895 fee.
- Is the Chase Sapphire Reserve worth it? The same for the $795 fee.
- Chase Sapphire Reserve vs Amex Platinum compares the two side by side, fee for fee.
- Citi Strata Elite vs Amex Platinum and Citi Strata Elite vs Chase Sapphire Reserve show what the $595 option gives up.
- Amex Gold vs Platinum and Chase Sapphire Preferred vs Reserve cover the cheaper step-down in each family.
For the full picture of each card, see our Amex Platinum guide and Sapphire Reserve guide. For all three premium cards together, there is our three-way comparison.
The Verdict
I would not cancel either card on principle. But I would not pay either fee on autopilot anymore.
The Platinum at $895 is a card for people who live in its credits and its lounges. If that is you, the $200 increase is more than covered by the bigger hotel credit and the new Resy and Uber One credits. If it is not you, the math that was borderline at $695 does not work at $895.
The Reserve at $795 is the easier keep for most people who already like Chase points, thanks to the automatic $300 travel credit and the dining credit. But the 8x Chase Travel earning only helps if you will book there, and the new 1x on other travel is a real step backward for everyone else.
The best use of ten minutes this week: pull up your renewal date, list the credits you used last year, and add them up. If the total is below your fee, you have your answer before the notice arrives. The free MaxPoints calculator will tell you what your regular spending earns on each card, so you can see what you would give up by switching.
Frequently Asked Questions
Q: What is the new annual fee for the Amex Platinum? A: $895, up from $695. New applicants paid it from the September 2025 refresh, and existing personal cardmembers started paying it on renewals from January 2, 2026. Authorized users are $195.
Q: What is the Chase Sapphire Reserve annual fee now? A: $795, up from $550. New applicants paid it from June 23, 2025, and existing cardholders pay it on renewals on or after October 26, 2025. Authorized users are $195, up from $75.
Q: Did the Amex Platinum earn rates change with the fee increase? A: No. It still earns 5x on flights booked directly with airlines or through Amex Travel and on prepaid hotels through Amex Travel, and 1x on everything else. The change was in the credits.
Q: Did the Chase Sapphire Reserve earn rates change? A: Yes. Chase Travel went from 5x to 8x, direct flights and hotels from 3x to 4x, and other travel dropped from 3x to 1x. Dining stayed at 3x.
Q: Is the Amex Platinum still worth $895? A: It is if you would use about $900 of its credits anyway, such as Uber, digital entertainment, airline fees and a hotel credit, and you value the lounges. If you use only one or two credits, it is hard to justify.
Q: Is the Chase Sapphire Reserve still worth $795? A: For many existing Chase customers, yes, if you use the $300 travel credit and the dining credit and book through Chase Travel. If you mostly book travel on third-party sites, the new 1x rate on other travel works against you.
Q: What should I do before my renewal date? A: Add up the credits you really used in the past year and compare the total with the fee. If it falls short, contact the issuer about a lower-fee card in the same family rather than paying a fee the card does not earn back.
Sources: American Express for the Platinum fee and benefits; Chase for the Sapphire Reserve. Renewal timing for existing cardholders is as widely reported by CNBC Select and NerdWallet. Fees, credits and eligibility change, so confirm current terms with the issuer before you apply or renew.